

LTCG, STT under scrutiny as Sitharaman opens door to capital gains tax review
Experts say the debate goes beyond tax cuts, with predictability, foreign investor confidence, household savings and government revenue at stake

Finance Minister Nirmala Sitharaman’s willingness to hear stakeholder views on long-term capital gains (LTCG) tax and securities transaction tax (STT) has reopened a debate over the competitiveness of India’s capital markets, with tax experts calling for a closer examination of the cumulative burden on investors and the consistency of rules across asset classes.
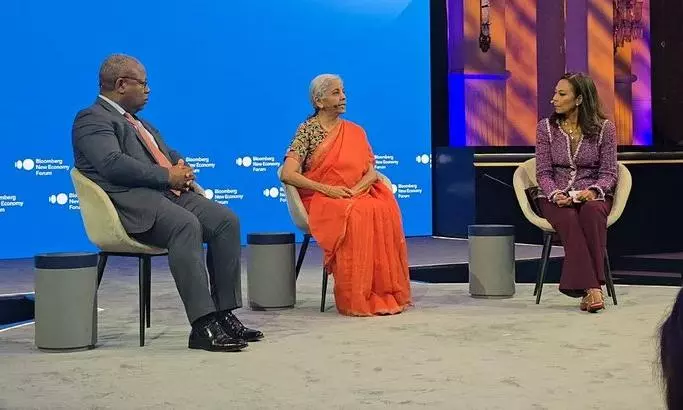
Speaking at the Bloomberg New Economy Forum in New Delhi on Tuesday (October 13), Sitharaman said the debate around LTCG, STT and the treatment of different asset classes was healthy, while cautioning that it was too early to indicate what the government might consider ahead of the next Union Budget.
Also read | Sensex jumps 1,109 pts as Sitharaman’s LTCG, STT remarks spark Budget hopes
Her remarks have raised expectations of a possible review, but do not constitute a commitment to reduce or abolish either tax. The policy challenge is to improve the attractiveness of Indian equities and encourage long-term investment without compromising revenue collection or efforts to curb speculative trading.
The discussion comes amid volatile foreign portfolio investor (FPI) flows, pressure on the rupee and concerns about the relative attractiveness of Indian equities. Although taxation is only one factor influencing investment decisions, market participants argue that a predictable and competitive regime can help reduce friction and improve investor confidence.
The STT-LTCG overlap
At the centre of the debate is the coexistence of STT, levied on specified securities transactions, and LTCG tax, which applies to qualifying realised gains.
STT was introduced in 2004, and qualifying long-term gains on listed equities were subsequently exempt from capital gains tax. The reintroduction of LTCG tax in 2018 brought the two levies into focus again, prompting questions about the cumulative cost of investing in listed shares.
The taxes operate differently: STT is linked to specified transactions, while LTCG tax depends on taxable gains. The concern is therefore not necessarily that the same income is taxed twice, but whether the combined burden is appropriately calibrated, particularly for investors who hold shares over extended periods.
Sandeep Sehgal, Partner – Tax & Valuations at AKM Global, says certainty is as important as the tax rate for investors making long-term decisions.
“For long-term investors, certainty in the tax regime is as important as the tax rate itself and frequent changes in capital gains taxation can complicate investment decisions and long-term financial planning,” Sehgal says.
He argues that a review could simplify the rules, improve consistency across asset classes and provide investors with greater clarity and confidence.
The existing framework also raises questions about differences in holding periods, tax rates and exemptions across asset classes. The removal of indexation benefits for most capital assets has further sharpened concerns that taxable nominal gains may not always reflect inflation-adjusted returns.
For specified listed equity investments, long-term gains exceeding the annual exemption of ₹1.25 lakh are generally taxed at 12.5%, subject to applicable conditions. Investors and advisers are debating whether the exemption provides sufficient relief as household participation in financial markets expands.
From tax parity to global competitiveness
The policy debate has evolved since LTCG tax was reintroduced in 2018. The original rationale included tax neutrality, parity across asset classes and revenue mobilisation. Today, experts are also examining whether the framework is competitive enough to attract and retain domestic and overseas capital.
Richa Sawhney, Partner – Tax at Grant Thornton Bharat, says: “The rationale for reintroducing LTCG on listed equities in 2018 was driven by concerns around tax neutrality, parity across asset classes and revenue mobilisation. The debate today is different.”
Also read | UPI MDR rollout deferred until after Diwali: What consumers and merchants need to know
“It is centred on whether India’s capital market framework is sufficiently competitive to attract and retain long-term domestic and foreign capital,” she adds.
Sawhney sees the budget consultation process as an opportunity to assess whether the current regime remains aligned with India’s evolving economic and investment priorities.
A review could consider the interaction between transaction taxes and capital gains taxation, the treatment of different asset classes and the predictability of rules. However, any move towards greater uniformity would need to account for differences in investment risk, liquidity and economic purpose.
Foreign investors seek certainty, not just lower rates
The debate has particular significance for foreign portfolio investors, whose decisions are influenced by global interest rates, currency movements, valuations, corporate earnings and geopolitical risks, alongside taxation.
Tejas Desai, Partner and Leader, Financial Services Tax, India, says the competitiveness of Indian capital markets deserves renewed attention amid foreign investor outflows and pressure on the rupee.
“While global factors, relative valuations and corporate earnings remain key drivers of foreign investor flows, the cumulative burden of capital gains tax and Securities Transaction Tax (STT) also influences the attractiveness of Indian equities,” Desai says.
He calls for “a holistic review of the tax burden on foreign portfolio investors, including the role of STT, to improve net returns and reduce friction costs.”
Desai also highlights the need for tax certainty following the Tiger Global judgment, particularly in the application of treaty benefits in line with India’s international commitments, including for grandfathered investments.
A more predictable regime could improve confidence, but tax reform alone is unlikely to reverse foreign outflows if global conditions or market valuations remain unfavourable.
What it means for households and govt revenue
For domestic investors, a higher exemption threshold, lower effective tax burden or incentives for longer holding periods could improve post-tax returns and support long-term wealth creation. A simpler framework could also encourage households to consider financial assets alongside traditional investments such as gold and real estate.
However, tax relief is not sufficient on its own to change savings behaviour. Financial literacy, market volatility, household risk tolerance and access to suitable investment products will remain important determinants of participation.
For the government, the trade-off is between immediate revenue and the potential longer-term benefits of deeper capital markets. Lower tax rates or higher exemptions could reduce collections, while greater investment and participation might support capital formation. Any revenue gains from increased activity, however, would be uncertain and should not be assumed to offset the fiscal cost automatically.
Also read | Bloomberg report’s USD 170 bn India opportunity comes with a catch
The design of reform will also matter. Rationalising STT on delivery-based investments could lower costs for long-term investors, while broad-based reductions in transaction taxes would have different implications for derivatives trading and speculative activity.
Balancing investor returns and govt revenue
The immediate question is not whether India should abandon capital gains taxation, but whether the current framework can better balance revenue needs with investment incentives.
A comprehensive review would assess the combined effect of STT and LTCG tax, differences in asset-class treatment, inflation’s impact on real returns and certainty in tax administration. It would also need to evaluate fiscal consequences and avoid creating new distortions between investment categories.
As Sehgal argues, the objective should be “a simpler, more consistent and predictable framework that balances investor confidence with the government’s revenue objectives.”
Sitharaman’s remarks have opened the door to that discussion. Whether it leads to meaningful changes will depend on the government’s assessment of the economic benefits, fiscal costs and implications for market behaviour. For investors, the most valuable outcome may ultimately be a regime that offers not only reasonable taxation, but also the confidence to invest for the long term.