

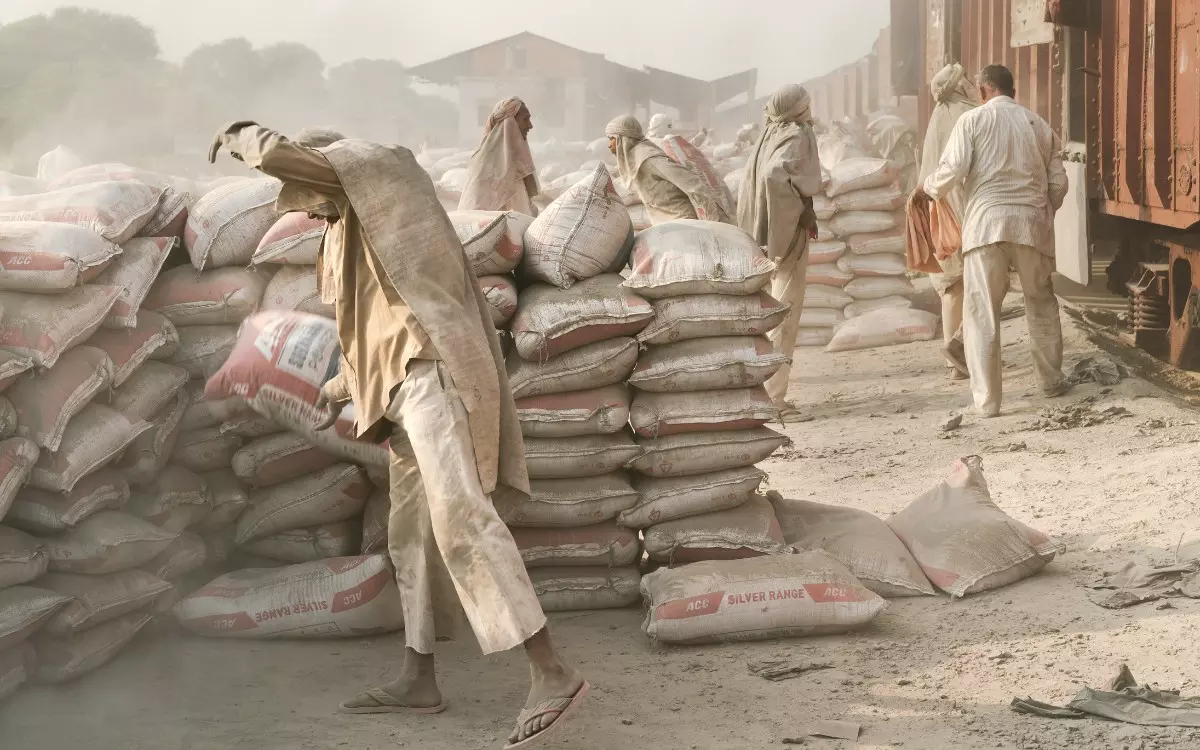
Cement sector’s Rs 75,000 cr capex push may reshape costs, capacity and credit risks
Domestic cement makers are set to invest about Rs 75,000 crore across fiscal 2027 and fiscal 2028, around 10 per cent higher than the previous two-fiscal-period outlay, according to Crisil Ratings

The cement industry’s planned investment of around Rs 75,000 crore over the current and next financial years could influence the cost and pace of building homes, roads and infrastructure. Capacity additions are expected to broadly match demand, while renewable energy and more efficient logistics could help manufacturers manage costs, potentially affecting builders, homebuyers and public infrastructure projects across the country over time.
Domestic cement makers are set to invest about Rs 75,000 crore across fiscal 2027 and fiscal 2028, around 10 per cent higher than the previous two-fiscal-period outlay, according to Crisil Ratings. The analysis covers 18 companies, or around 90 per cent of India’s installed capacity.
The industry added 84 million tonnes per annum (MTPA) of capacity in the preceding two fiscals, taking installed capacity to 718 MTPA as on March 31, 2026. Crisil expects capacity to reach around 1,110-1,120 MTPA across fiscals 2027 and 2028. With utilisation estimated at about 70%, additions should broadly match incremental demand.
Grinding units, green energy to drive spending
Around two-thirds of incremental capacity is expected to come from grinding units, with the rest from clinker capacity. Locating grinding units closer to markets can improve logistics efficiency. Clinker is commissioned in phases and can create temporary surplus that takes one to three years to be absorbed.
Also read: Solar demand is soaring, but manufacturers face a growing credit crunch in FY27
Crisil Ratings director Sayan Kulkarni said the industry was likely to add 110-120 MTPA over the two fiscals, with additions broadly aligned to demand. Capacity expansion will drive annual capex.
Spending will also fund green energy and efficiency upgrades. Renewable sources already meet around 40 per cent of the sector’s power requirement, a share expected to rise to nearly 50 per cent by the next fiscal, helping offset cost pressures.
Fuel costs weigh on cement profitability
Operating profitability is expected to soften to Rs 875-900 per tonne this fiscal, from around Rs 980 per tonne in fiscal 2026, Crisil said. Petcoke and international coal prices surged around 35 per cent year-on-year on average in the first half of the current fiscal.
Power and fuel account for more than a quarter of total costs. Their cost has increased by Rs 100-125 per tonne, or about 10 per cent, over the previous fiscal. Price increases may partly offset the rise.
Also read: Centre widens export support net, raises airfare subsidy to 95pc for small exporters
Operating profit is expected to recover to around Rs 970 per tonne next fiscal, assuming commodity prices ease, renewable energy use increases, blended cement gains share and cost-efficiency measures continue. Cement prices will depend on fuel costs, demand and producers’ ability to pass on increases.
Leverage to peak in fiscal 2027
The capex cycle is likely to raise leverage temporarily. Crisil expects capex-to-Ebitda to rise to 0.8 times in fiscal 2027, against a decadal average of 0.65 times, increasing the need for debt funding. Debt-to-Ebitda is projected to peak at 1.5 times, its highest level in five fiscals, though still controlled.
The ratio is expected to ease to 1.2-1.3 times in fiscal 2028 as profitability and cash flows recover from newly commissioned capacity. Crisil Ratings associate director Satyarth Shah said sustained capex and lower profitability would increase funding needs, but robust balance sheets and resilient cash flows should help maintain stable credit profiles.
Commissioning delays or a slower profit recovery could postpone deleveraging.
For India’s construction economy, the investment signals confidence in demand and a larger production base. The test will be whether companies add capacity in step with consumption, control energy costs and finance expansion without allowing debt to rise beyond manageable levels.